There was not much change in the North American lumber market following the Thanksgiving long weekend in Canada.
Customers, resellers and end-users alike, continued their now long-entrenched habit of just-in-time buying and not stocking inventory. The sentiment that prices might drop remains ongoing. For their part, producers reduced prices on some items while being able to hold firm on others.
Each lumber sale was its own individual transaction, with final prices varying widely across species and region. As always; the business of selling wood in North America decidedly hinges on relationships. For the time being sawmills were able to reject steep counter-offers, as order files still run at approximately two weeks.
Expectations are for the usual slow-down, perhaps with softer prices, as true winter weather starts to come on.
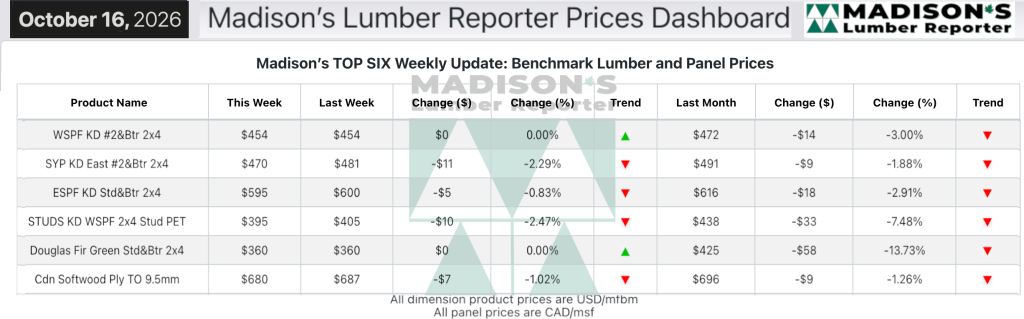
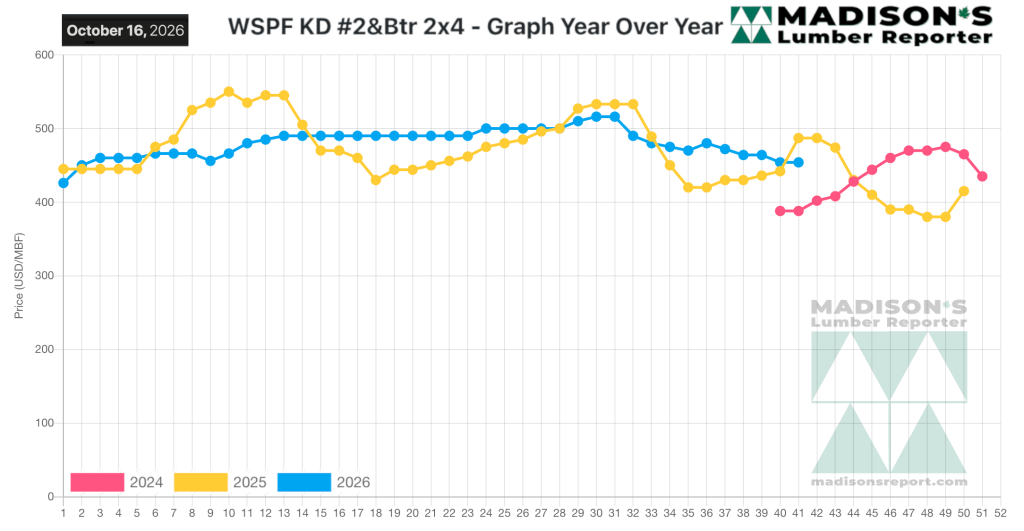
In the week ending October 16, 2026 the price of Western Spruce-Pine-Fir 2×4 #2&Btr KD (RL) was US$454 mfbm, which was flat from the previous week, said weekly forest products industry price guide newsletter Madison’s Lumber Reporter.
That week’s price was down -$18, or -4%, from one month ago when it was $472.
Much of the lumber market demonstrated the ongoing flat-to-downward trend seen broadly in S-P-F and Southern Pine.
To subscribe to Madison’s Lumber Reporter, simply fill out an order form here: https://madisonsreport.com/subscribe/
KEY TAKE-AWAYS:
• Producers of Western-SPF in the US kept their posted standard dimension lumber asking prices flat at the previous week’s levels.
• There was increased inquiry for lower grade material used for pallets and packaging in advance of a protracted holiday season.
• Western-SPF buyers in Canada covered their near-term needs with little to no trouble.
• Smaller sawmills with mild inventory accumulations accepted price concessions on a case-by-case basis.
• Buyers of Eastern-SPF were opportunistic; most looked for discounts below published prices.
• In the East a few retail purchasers sought more coverage where they felt undersupplied for remaining 4Q needs.
• Freight was a relentlessly complicating factor in every deal, in both the Great Lakes and Toronto markets.
• Supply of Southern Yellow Pine lumber resoundingly outstripped anemic demand again.
• Tumbling SYP prices didn’t look to be approaching a bottom, leading many to speculate that sawmills had some tough decisions to make.
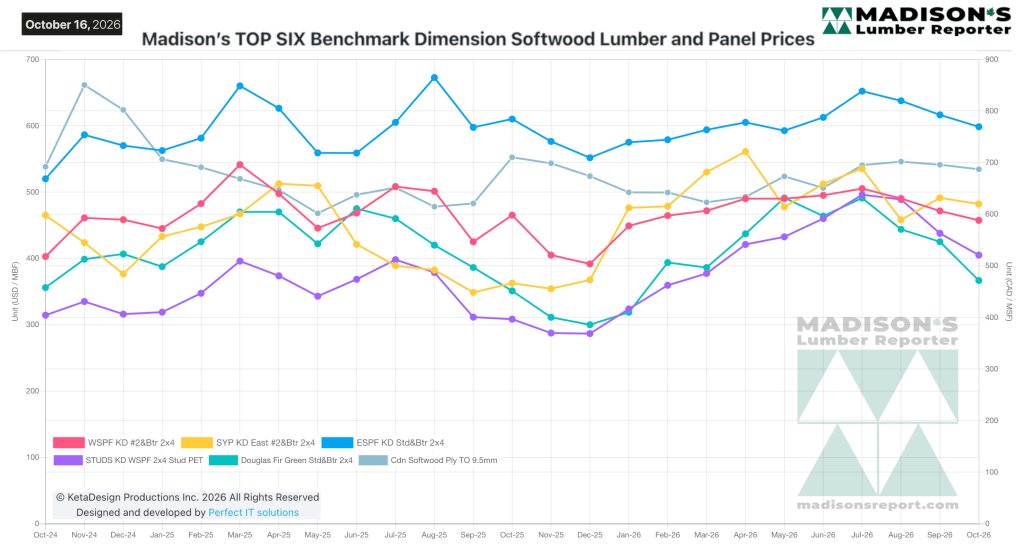
Madison’s Benchmark Top-Six Softwood Lumber and Panel Prices: Monthly Averages